
PRIVATE CREDIT
NCD vs term loan — which is right for your business?
Non-Convertible Debentures and term loans both provide debt capital — but they serve very different situations. Here is how to choose.
Read the analysis →
KBA Tower 5, 14th Floor, Noida
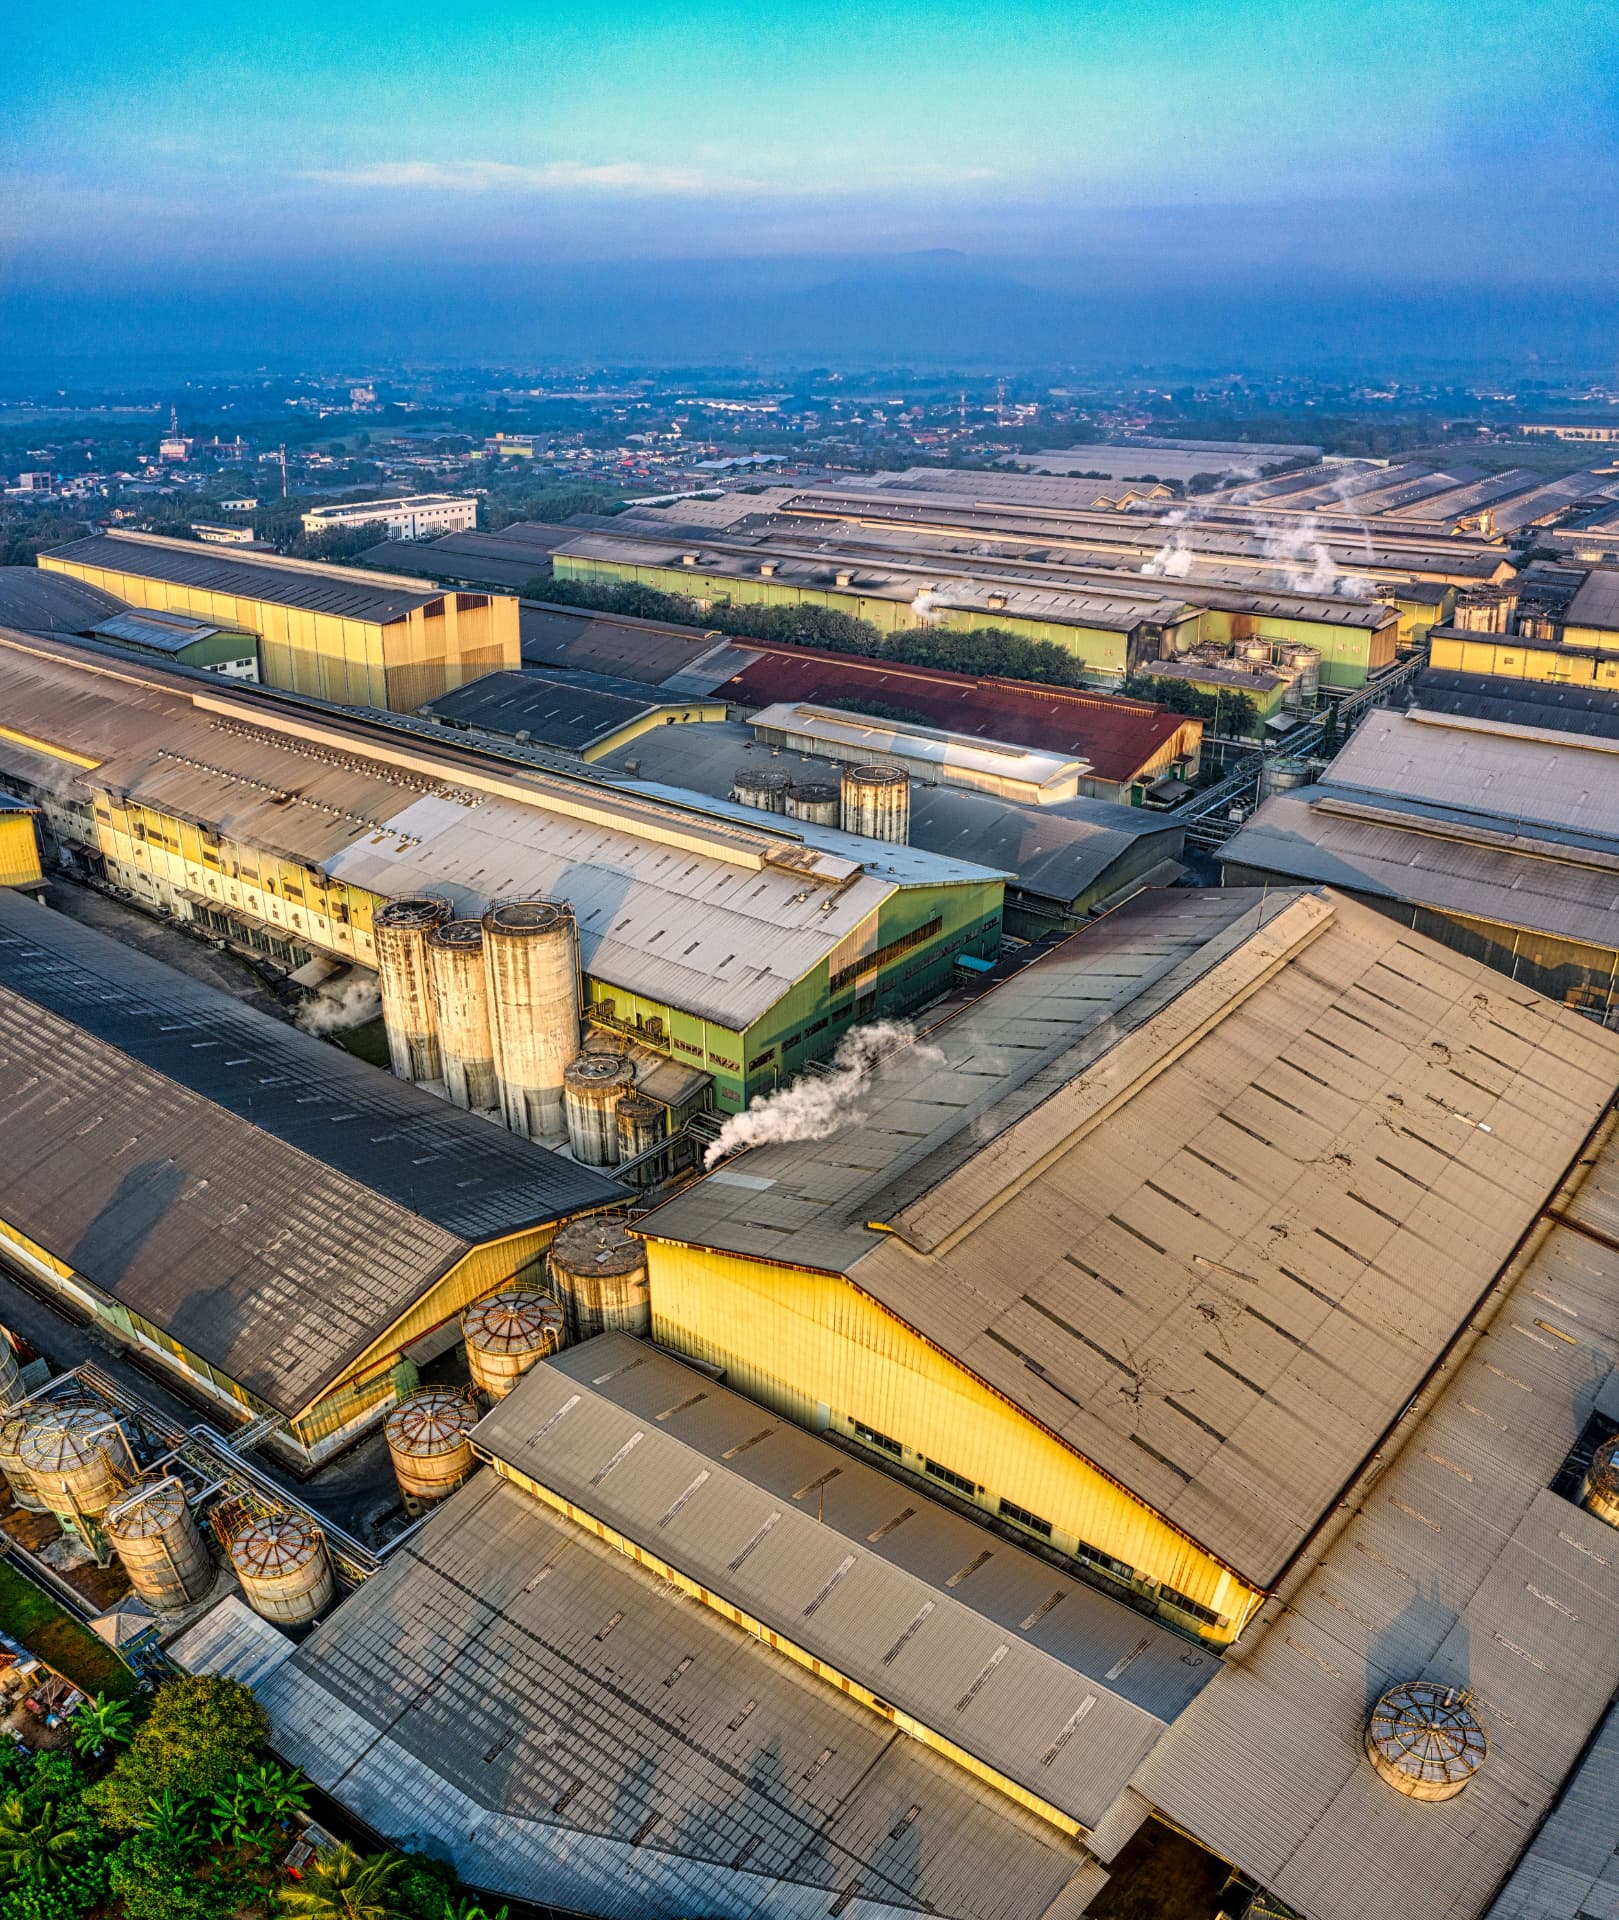
Private Credit→MSME & Manufacturing Finance
Eone Capital is a specialist private credit and debt syndication advisory firm in India. We arrange structured debt of ₹30 crore and above for real estate developers, MSME manufacturers, and healthcare operators — working with banks, NBFCs, AIFs, and private credit funds to place the right instrument with the right lender.
Most mid-sized manufacturers and MSME companies have outgrown their existing bank relationships but have not yet accessed the full range of private credit and structured debt instruments available to them. Eone Capital assesses the business, structures the right instrument — whether a term loan, NCD, or a bespoke structured facility — and places it with the lender most suited to the profile and requirement.
NCD structuring is a core capability we bring to MSME mandates — particularly where the requirement does not fit a standard bank product in tenure, ticket size, or repayment structure. We design the instrument, prepare the information memorandum, and place privately with institutional investors, family offices, and AIFs.
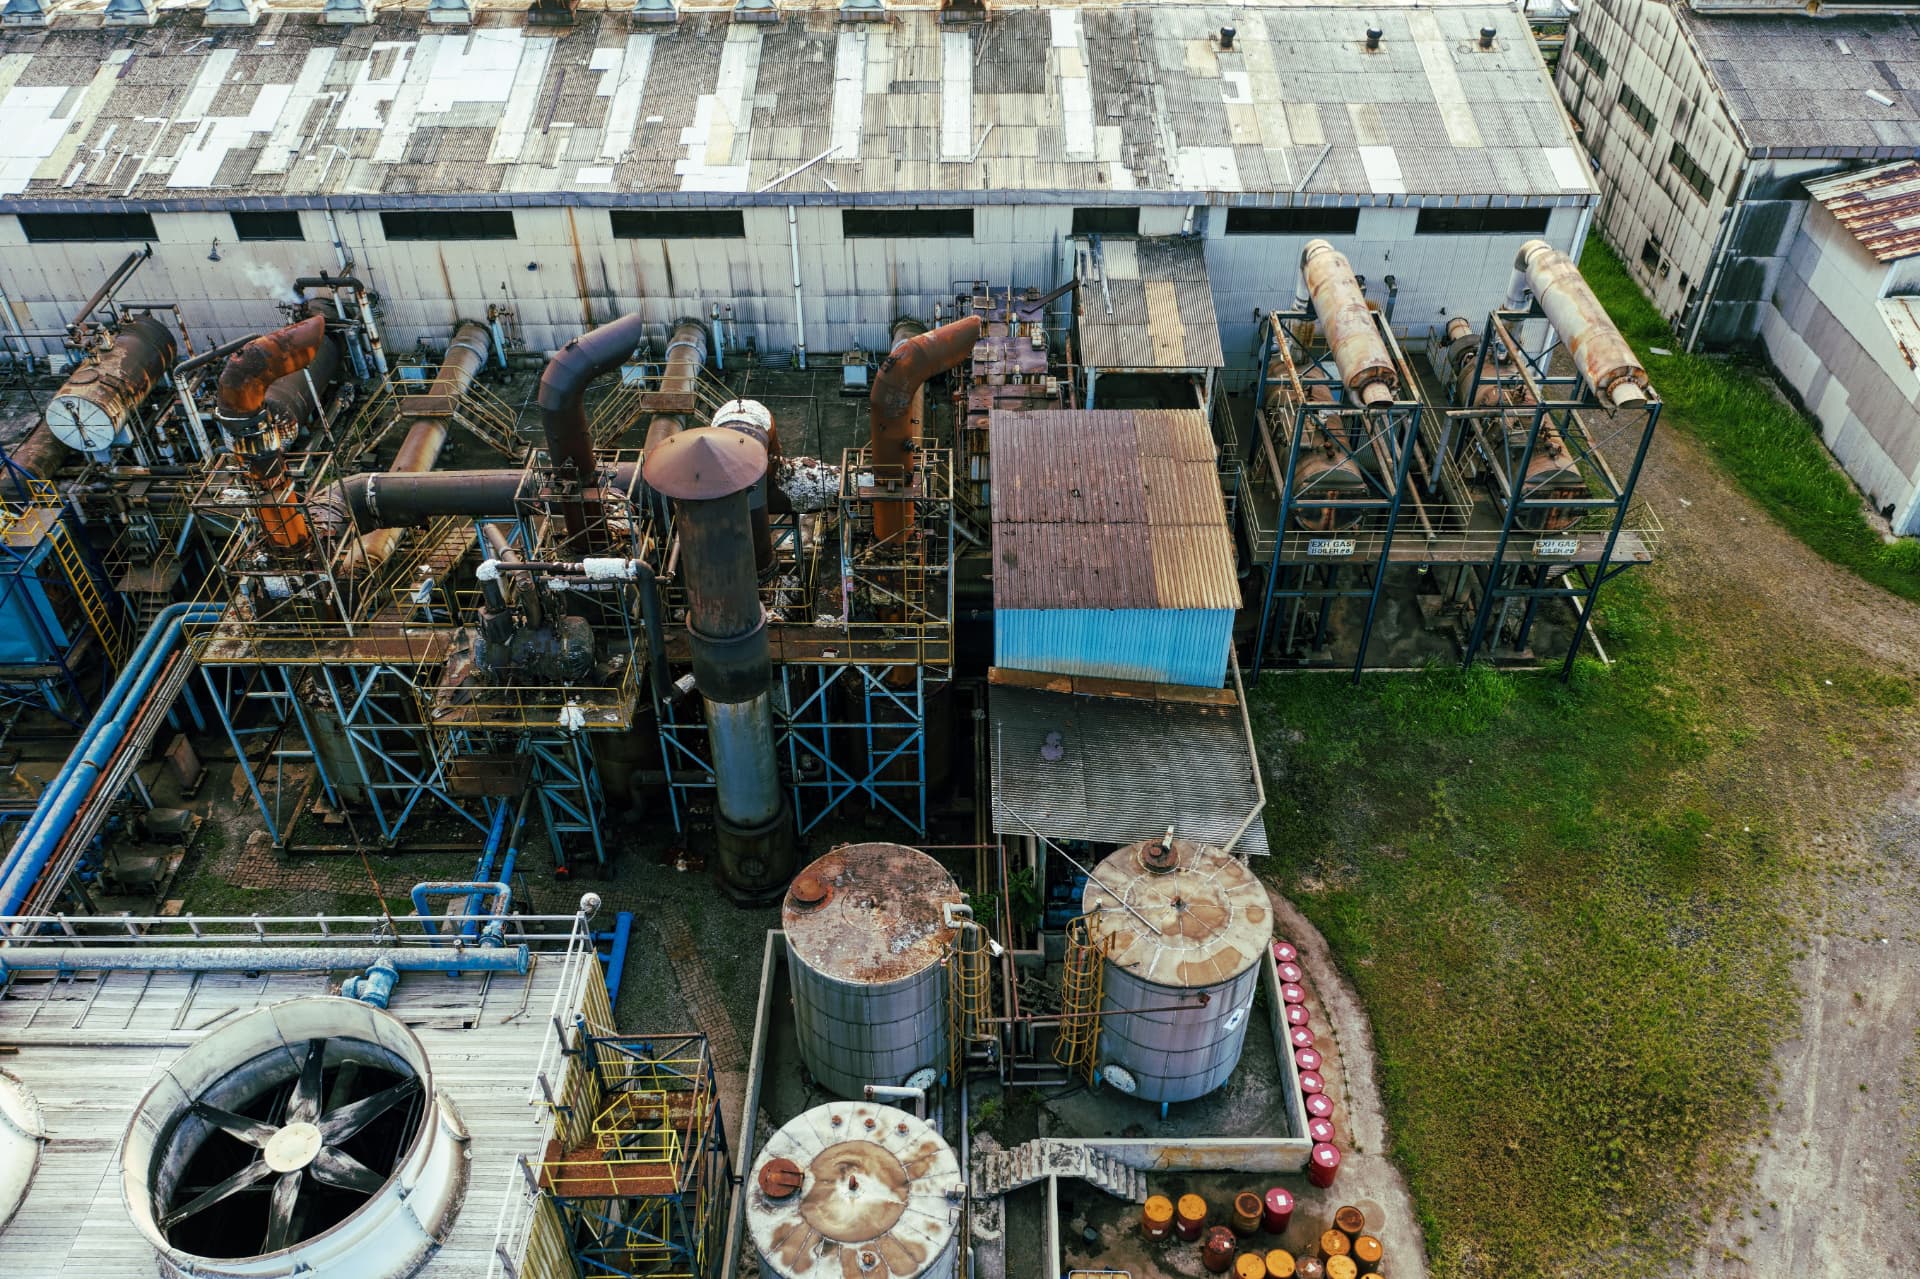
Debt arranged for capacity expansion — new plant, additional production lines, warehouse infrastructure, or geographic expansion. Structured against existing cash flows and projected revenue. Instrument determined by the asset profile and tenure required — term loan or NCD depending on fit.
Replacing expensive existing debt — high-cost working capital loans, overdraft facilities, or legacy term loans — with better-structured, lower-cost facilities. We assess the full liability stack and identify the right refinancing route — bank, NBFC, or NCD placement.
Debt structured to fund the acquisition of another manufacturing unit, company, or business asset. Secured against the combined balance sheet and the acquired asset. Structured as a term loan or NCD depending on the transaction complexity and lender appetite.
Free Checklist
Download our Private Credit Readiness Checklist — the exact questions a Category II AIF or NBFC will ask during due diligence. Know the answers before they ask.
Non-Convertible Debentures are a privately placed debt instrument that offers MSME and manufacturing companies access to capital structures a standard bank loan cannot provide — longer tenure, flexible repayment, larger ticket sizes, and lender profiles that include family offices and institutional credit funds.
Eone Capital structures the NCD — coupon rate, tenure, security package, put and call options — and places it privately with the investors best suited to the credit profile. We manage the full process from term sheet through documentation and allotment.
When the requirement exceeds what a single bank will lend, when tenure beyond 5 years is needed, or when the business needs a lender who understands the specific sector and growth profile.
Family offices, AIFs, private credit funds, and institutional investors seeking fixed-income returns from mid-market corporate credit.
₹30 crore and above. NCDs can be structured in tranches for larger requirements with multiple investors subscribing.
Structuring adviser and placement agent. We design the instrument, prepare the information memorandum, and place with the right investors.
Manufacturing companies, industrial businesses, and mid-market corporates with physical operations and asset-backed balance sheets.
Established businesses with consistent, verifiable revenue and positive EBITDA. We work with businesses that have real cash flows — not projections.
₹30 crore and above. The requirement must justify specialist debt structuring — either in size, complexity, instrument type, or lender profile.
Expansion, refinancing, or acquisition. We do not arrange working capital lines or small-ticket facilities.
Revenue, EBITDA, debt service capacity, asset base, and liability stack assessed before we engage.
Right instrument selected — term loan, NCD, or structured facility. Security package, tenure, coupon, and repayment designed for the specific requirement.
Placed with the specific bank, NBFC, AIF, or family office whose current deployment appetite matches the transaction profile.
Managed through term sheet, due diligence, documentation, and disbursement. We earn at close.
Related Reading
PRIVATE CREDIT
Non-Convertible Debentures and term loans both provide debt capital — but they serve very different situations. Here is how to choose.
Read the analysis →PRIVATE CREDIT
A credit information memorandum is the primary document for private credit placement. Here is what the seven sections must cover and what lenders flag immediately.
Read the analysis →PRIVATE CREDIT
Category II AIFs are the primary vehicle for private credit. Here is how they raise capital, evaluate borrowers, and structure and monitor loans — from a borrower's perspective.
Read the analysis →₹30 crore and above. Manufacturing and mid-market. All India.
Start a Conversation